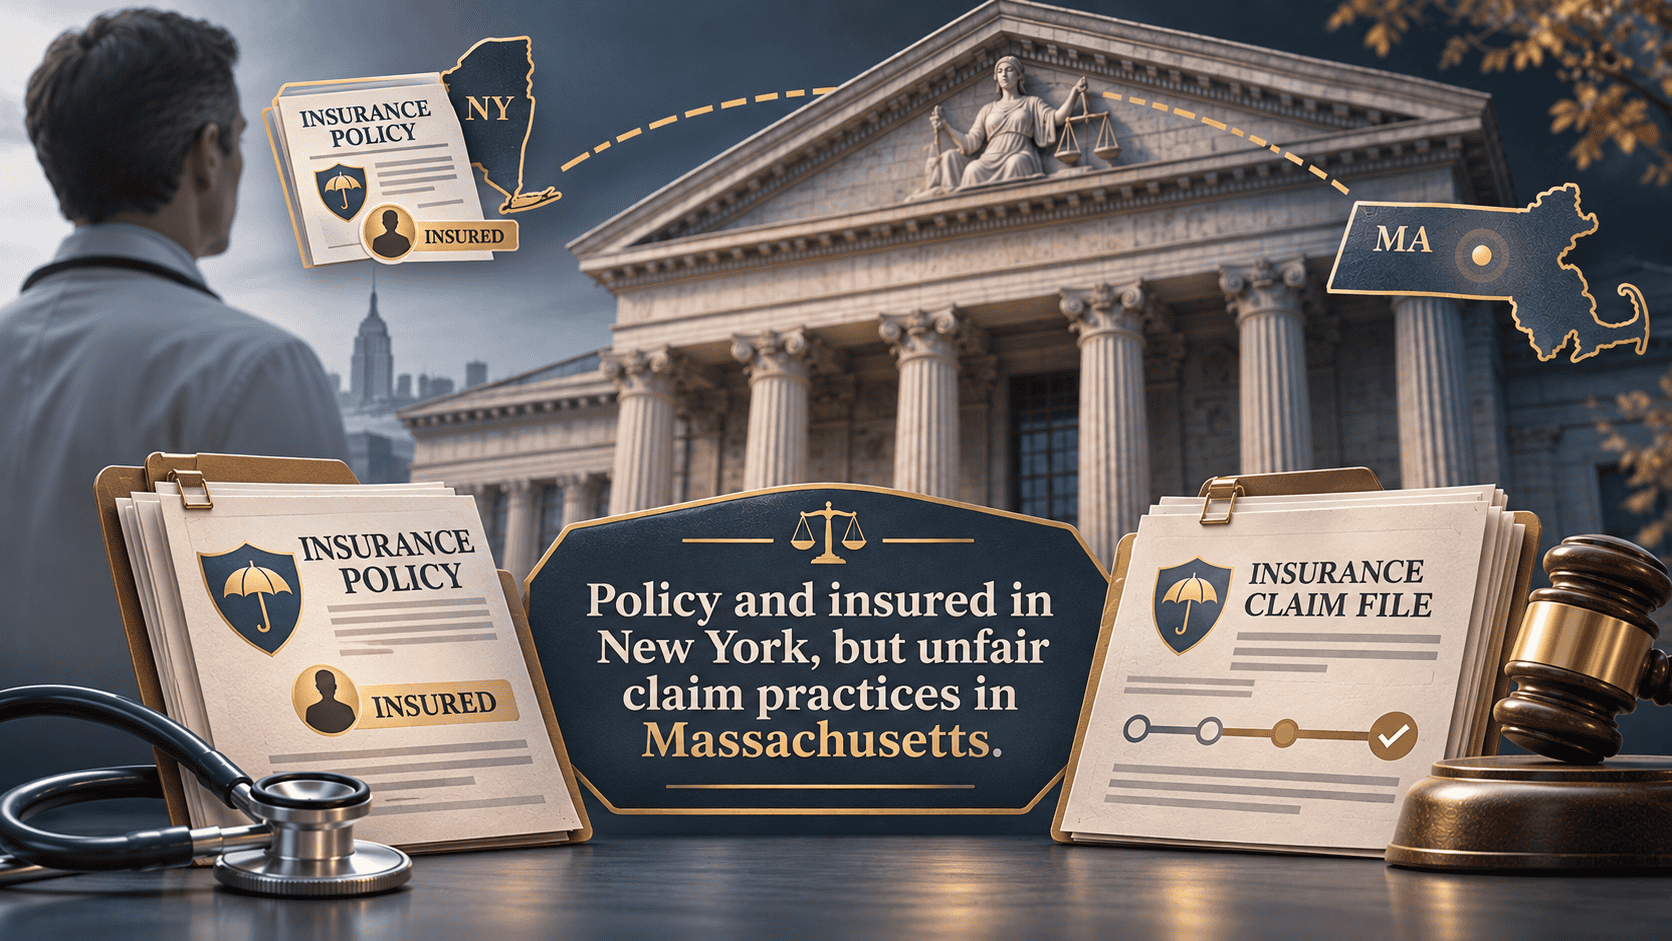
The Massachusetts Appeals Court has upheld a Chapter 93A judgment against The Paul Revere Life Insurance Company arising from its handling in Massachusetts of a New York physician’s disability claim under a New York-issued insurance policy. The court agreed that the unfair claim settlement practices claim was independent of the insurance contract and properly evaluated under tort-based choice-of-law principles, which consider where the alleged wrongful conduct occurred and which state has the most significant relationship to the dispute.
The panel also affirmed findings that Paul Revere failed to maintain reasonable investigation standards and delayed payment after liability became reasonably clear. Although the insurer paid benefits retroactively, the delayed payment resulted in a judgment for lost interest, statutory damages, legal fees and costs.
The October 19, 2026, memorandum in Constantino v. The Paul Revere Life Insurance Company, No. 25-P-811, was issued under Appeals Court Rule 23.0. It may be cited for persuasive value, but is not binding precedent.
Paul Revere 93A Ruling: Why Massachusetts Law Applied
Dr. Richard Constantino, an internist who lived and practiced in Rochester, New York, obtained his disability policy in New York in 1986. Paul Revere is a Massachusetts corporation, and the Superior Court found that the insurer received, evaluated and acted on his disability claim and internal appeals in Massachusetts.
Paul Revere argued that New York law should apply to the dispute. The distinction mattered: as the Appeals Court noted, New York law provides no private action for consumer protection violations comparable to Massachusetts Chapter 93A.
In April 2022, Superior Court Judge Kenneth W. Salinger ruled that the statutory claim concerned allegedly unfair claims administration, not rights created by the insurance contract. Applying choice-of-law principles used for tort claims, he found Massachusetts had the most significant relationship to the alleged misconduct and parties.
The Appeals Court agreed that the claim was tort-like and that the trial judge properly selected that framework. It did not decide Paul Revere’s separate argument that New York law should govern even under that framework: the insurer first raised that argument in its appellate reply brief, too late for consideration.
Constantino’s claim proceeded under Chapter 93A, Section 9. The decision does not resolve how the different territorial limitation in Section 11 would apply to a business-to-business claim.
Paralyzed Feet and a Disputed Policy Definition
The policy provided presumptive total disability benefits if an insured totally and irrecoverably lost the use of both feet, regardless of whether the insured could continue working or required medical treatment.
In February 2017, Constantino’s physician described his paralyzed feet as “significantly useless.” Another physician reported that one toe and portions of two others had been amputated and characterized his feet as “functionally useless.” Constantino could walk with ankle braces and a walking stick, but Paul Revere acknowledged that he could not move or feel his feet when walking.
Paul Revere nonetheless denied presumptive disability benefits because he could “ambulate independently.” In findings later quoted by the Appeals Court, the Superior Court judge said the insurer disregarded evidence that the feet were no more useful than “amputated stumps.”
After Constantino’s attorney threatened litigation in March 2019, a Paul Revere physician reconsidered the record without new medical information and concluded that Constantino’s “ambulation is in spite of his feet, rather than with the assistance of his feet.” On May 22, 2019, the insurer approved presumptive total disability benefits retroactive to February 13, 2017.
Claims Investigation and Settlement Findings Affirmed
Following a jury verdict on breach of contract and a separate bench trial, the Superior Court found violations of Chapter 176D, Section 3(9)(c), concerning standards for prompt investigation, and Section 3(9)(f), concerning prompt settlement once liability becomes reasonably clear. Those findings supported the Chapter 93A judgment.
Paul Revere argued on appeal that it had made a reasoned, albeit mistaken, interpretation of the policy. The Appeals Court instead found sufficient support for the trial judge’s determination that the insurer repeatedly shifted its interpretation and effectively failed to investigate the claim meaningfully for two years. Its eventual payment did not erase the earlier delay.
Constantino did not prevail on every claim. The court affirmed dismissal of his negligence, misrepresentation and intentional-infliction-of-emotional-distress counts. It also upheld limitations on his claims for earlier benefits. His inability to perform hospital work beginning in 2013 did not establish total disability under the policy because his occupation included an office practice; the policy distinguished total from residual disability. The court also enforced the policy’s three-year contractual limitations provision.
A Small Interest Loss and a Six-Figure Judgment
The parties stipulated that the interest lost because of the delayed benefits totaled $4,312.98. The trial judge doubled that amount under Chapter 93A to $8,625.96. The February 2025 judgment also included $2,494.55 in prejudgment interest, $14,798.47 in costs and $125,000 in attorney fees, producing a total judgment of $150,918.98.
The Appeals Court affirmed the judgment and held that Constantino could seek additional reasonable attorney fees and expenses incurred in defending Paul Revere’s unsuccessful cross-appeal on the Chapter 93A claim. It did not set an appellate fee amount.
For Massachusetts insurers with claims personnel administering policies issued elsewhere, the decision illustrates that the location of claims-handling conduct can matter to a Chapter 93A choice-of-law analysis. It does not mean Massachusetts law necessarily governs every out-of-state policy handled here: the result depended on the particular statutory claim, e.g., M.G.L. c. 93A, § 9 (Individual insureds) vs. § 11 (Commercial Insureds), the trial court’s findings, and arguments properly preserved on appeal.
Owen Gallagher
Insurance Coverage Legal Expert/Co-Founder & Publisher of Agency Checklists
Interested in connecting with me? Call me directly at 617-598-3801.