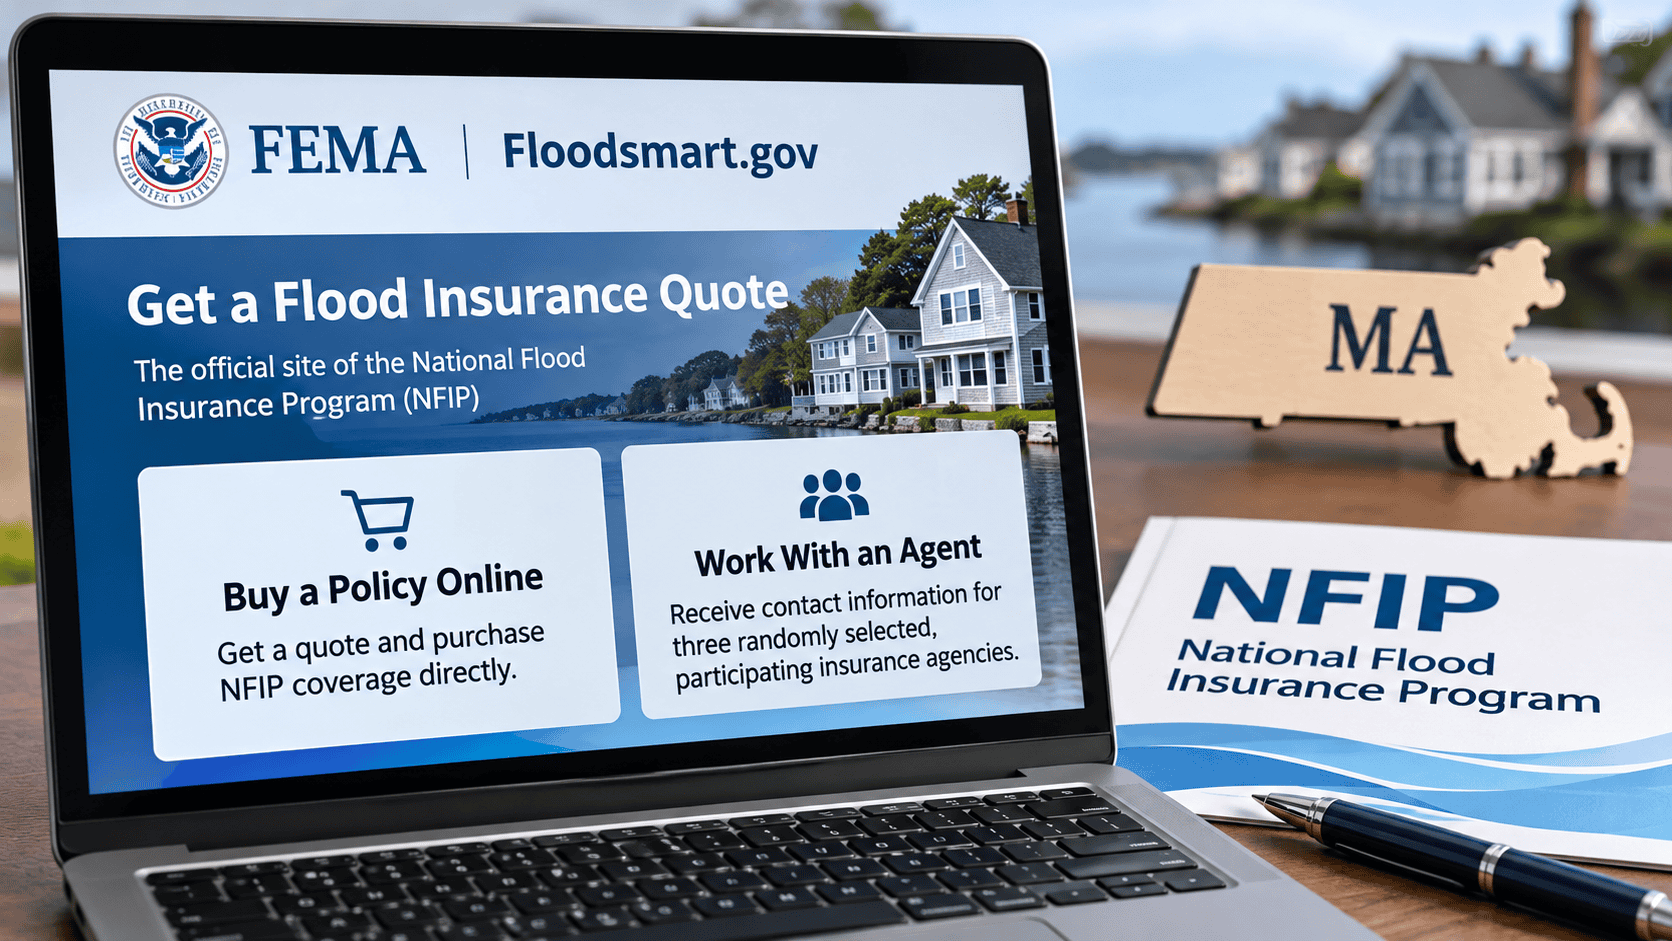
FEMA’s new online purchasing option allows consumers to buy NFIP coverage without an agent or receive contact information for three randomly selected participating insurance agencies.
The Federal Emergency Management Agency has introduced a direct online purchasing option for National Flood Insurance Program (NFIP) policies, allowing consumers to obtain quotes and complete purchases through Floodsmart.gov without using an insurance agent.
The October 20, 2026, launch introduces another distribution channel for the federal flood insurance program, which provides approximately $1.2 trillion in coverage to 4.4 million policyholders nationwide. The service is available to consumers in almost 22,700 participating NFIP communities.
Although consumers can purchase policies directly, FEMA has retained an agent-assisted purchasing option. If the consumer selects this option, they receive referrals to three randomly selected insurance agencies. The arrangement raises questions about how the new direct sales channel will affect independent agents and the private insurers participating in the NFIP’s Write Your Own (WYO) program.
How FEMA’s New Online Purchasing Option Works
Under the new system, consumers enter basic information about their buildings into Floodsmart.gov to obtain a flood insurance quotation.
Once a quotation is generated, consumers can purchase the policy online or complete the transaction through an insurance agent.
Those choosing an agent-assisted purchase can share their quotation with an existing agent. Alternatively, Floodsmart.gov provides contact information for three licensed insurance agents in the consumer’s state.
FEMA says the online purchase process can be completed in minutes.
The announcement follows earlier efforts to expand digital access to the NFIP. FEMA’s February 2025 Direct to Customer Tools for Insurance Agents Fact Sheet described its online Quoting Tool and Agency Registry as complementary components of the existing distribution system.
The October 2026 launch adds the ability to complete an online purchase rather than requiring an agent-assisted transaction.
FEMA’s Agency Registry Offers Referrals to Participating Agencies
An important component of the platform is FEMA’s Agency Registry, which enables participating insurance agencies to appear in the NFIP Quoting Tool.
According to FEMA’s official Registry documentation, consumers receive contact information for three randomly selected agencies from the Registry.
The February 2025 fact sheet also establishes that registered agencies can receive quotations from consumers who choose to share them. FEMA instructs those agencies to follow up with customers, review their coverage selections, answer questions and assist with completing policies.
This provides a mechanism through which consumers using the federal quotation system can connect with participating independent agencies.
However, a customer receiving an agency’s contact information is not the same as the agency receiving a customer inquiry. The quotation-sharing mechanism requires the consumer to elect to share the information.
How Independent Agencies Can Participate
Insurance agencies interested in appearing in the NFIP Quoting Tool can apply through FEMA’s Agency Registry.
Participating agencies must provide identifying and contact information, including National Producer Numbers, states served and languages spoken.
The Registry also requires an agency to identify one WYO insurer or NFIP Direct affiliation for each registered location. FEMA specifies that this Registry requirement does not prevent an agency from placing NFIP business through other WYO insurers with which it has relationships.
Agencies whose NFIP-facing agents have not completed the required Flood Insurance Reform Act training may remain in the Registry database but will not appear in the Quoting Tool.
FEMA states that approved agencies appear in the tool immediately after approval and must revalidate their registration information every six months.
Its February 2025 fact sheet also cautions that agencies affiliated with WYO insurers not participating in the Registry program will not be available through the Quoting Tool.
Independent Agent Association Questions Federal Competition
The Independent Insurance Agents & Brokers of America, commonly known as the Big “I,” has expressed concerns about FEMA’s expansion into direct online flood insurance sales.
In an October 22 article published by IA Magazine, Raaed Haddad, the association’s director of federal government affairs, said the organization supports efforts to expand access to flood insurance but questions the federal government’s role in direct distribution.
Haddad wrote that FEMA’s decision to sell policies directly to consumers could bypass agents and WYO insurers.
The association has raised concerns about FEMA’s direct-to-consumer initiative since its initial development in 2022.
The Big “I” maintains that independent agents provide important services in preparing quotations, explaining coverage limits and deductibles, and helping consumers understand policy provisions.
The organization has called on FEMA to strengthen existing private-sector distribution partnerships rather than establish a competing sales channel.
Questions Remain About WYO Insurers and Policy Servicing
The NFIP’s existing distribution structure includes more than 48 private property and casualty insurers participating in the WYO program.
Under that arrangement, participating insurers write and service NFIP policies in their own names, receiving expense allowances for policies written and claims processed. The federal government retains responsibility for underwriting losses.
Licensed property and casualty insurance agents can sell NFIP coverage through participating WYO insurers or NFIP Direct.
FEMA’s October announcement does not explain whether policies purchased directly through Floodsmart.gov will be serviced through NFIP Direct or assigned to participating WYO companies.
It also does not address whether the new purchasing option will change existing commission arrangements or WYO expense allowances.
Consequently, the announcement establishes a new consumer purchasing channel but does not provide enough information to determine its financial or operational effects on the existing distribution system.
What the Change Means for Massachusetts Insurance Agencies
The new online purchasing option is available to eligible consumers in Massachusetts communities participating in the NFIP.
According to the Massachusetts Division of Insurance, there were 56,650 Massachusetts NFIP policyholders in 2024, up 4.3% from 54,339 in 2023 (DOI Annual Home Insurance Report CY2024, Figure 9, as of June 30 each year).
For Massachusetts independent agencies, FEMA’s announcement presents two developments: consumers now have an additional means of purchasing NFIP coverage without an agent, while agencies participating in the federal Registry have an opportunity to be presented to consumers seeking assistance.
The extent to which either option will affect agency-produced NFIP business remains unknown.
FEMA has not released information establishing how many consumers will purchase policies directly, how frequently consumers will select agent referrals or what proportion of online transactions will ultimately involve independent agencies.
The new purchasing option therefore creates an additional means of distributing federal flood insurance, while leaving important questions unanswered about its effects on existing agency and WYO relationships.